National Pension System (NPS) India 2026: 14% Employer Deduction, Entry Age 70 and 1:30 PM NAV Cut-off Explained

By Prathamesh C. | Financial Analyst | 12 min read | Published: September 28, 2026
Disclaimer: This article is for educational purposes only and should not be construed as formal financial advice. Tax rules and PFRDA circulars change, so verify current provisions with official sources or a qualified financial or tax professional before acting.
Key Takeaways
- The private-sector employer deduction under Section 80CCD(2) reaches 14% of Basic + DA in the New Tax Regime. On a ₹12,00,000 salary, that lifts annual tax savings from ₹37,440 to ₹52,416.
- PFRDA raised the maximum entry age from 65 to 70 years in December 2025 and extended account continuation to 85 years. Late entrants aged 60–70 face no lock-in.
- Under PFRDA’s August 4, 2026 circular, contributions cleared by the Trustee Bank before 1:30 PM (earlier 11:00 AM) receive same-day NAV.
The National Pension System (NPS) now admits new subscribers up to age 70, lets them stay invested until 85, and grants same-day NAV to contributions cleared by 1:30 PM. Each change widens who can use the scheme and how flexibly they can fund it.
NPS is a defined-contribution, market-linked pension framework created by the Government of India and regulated by the Pension Fund Regulatory and Development Authority (PFRDA) under the PFRDA Act, 2013. This analysis draws on PFRDA circulars, bank and Central Recordkeeping Agency documentation, and tax-law commentary to explain the architecture, tax mechanics, eligibility limits and exit rules.
How Is the National Pension System Structured?
NPS runs on a dual-tier account system tied to one portable, 12-digit Permanent Retirement Account Number (PRAN). Tier I is the locked retirement core, while Tier II is an optional, fully liquid investment pool that requires an active Tier I account.
Tier I vs Tier II: Two Accounts, One PRAN
Tier I carries statutory lock-in conditions and exit limits designed to enforce decades of accumulation. In return, only Tier I qualifies for deductions under Sections 80CCD(1), 80CCD(1B) and 80CCD(2).
Tier II has no lock-in and allows unrestricted withdrawals. Private-sector employees cannot claim a tax deduction on it, so it functions as a medium-term liquidity bucket rather than a retirement vehicle.
Table 1: NPS Tier I vs Tier II — Minimum Contributions, Withdrawal Rules and Tax Treatment
Compares the two NPS account types on purpose, entry requirement, minimum contributions, liquidity, tax deduction eligibility and exit commutation.
| Structural Dimension | Tier I (Pension Core) | Tier II (Investment Engine) |
|---|---|---|
| Primary Objective | Mandatory long-term retirement capital preservation | Voluntary investment and discretionary capital growth |
| Account Requirement | Mandatory foundation for NPS participation | Optional; requires an active Tier I account |
| Minimum Initial Contribution | ₹250 at account opening | ₹250 at account opening |
| Minimum Subsequent Contribution | ₹10 per transaction | ₹10 per transaction |
| Withdrawal Flexibility | Restricted; locked until age 60 or formal exit | Fully liquid; withdrawable at any time |
| Tax Deduction Eligibility | Sections 80CCD(1), 80CCD(1B) and 80CCD(2) | Non-deductible for private-sector employees |
| Corpus Commutation at Exit | Up to 60% tax-free lump sum; minimum 40% to annuity | 100% withdrawable; no mandatory annuity |

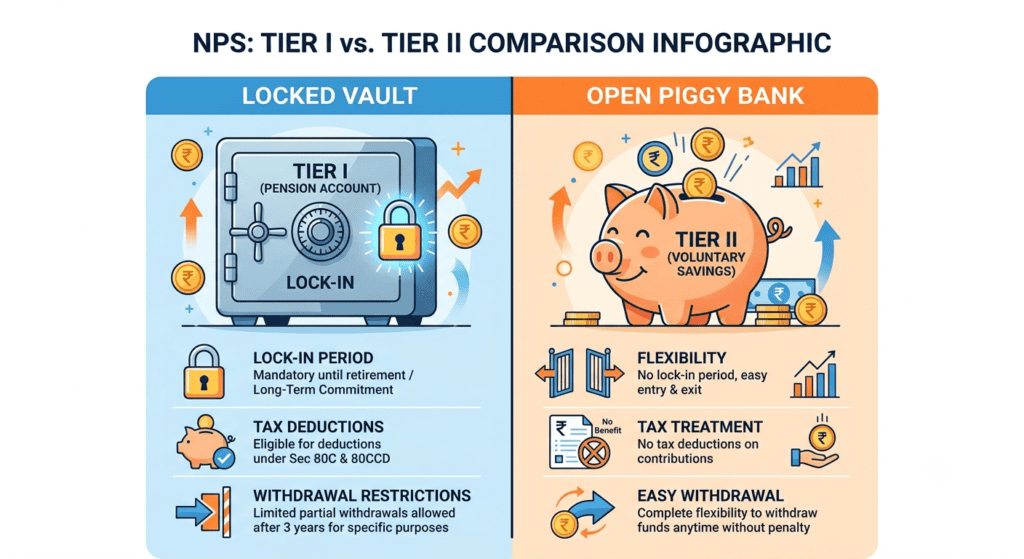
Infographic: NPS Tier I vs Tier II — the lock-in, tax and withdrawal differences in one view.
Related Read: Is There a 0% Interest Home Loan in India? What’s Actually Available (Up to ₹1.80 Lakh in Real Subsidy)
Active Choice vs Auto Choice: Who Controls Your Asset Mix?
Subscribers steer their investment strategy through two modes. Under Active Choice, the investor sets the percentage allocated to each of four asset classes.
Under Auto Choice, a lifecycle profile (Aggressive, Moderate or Conservative) shifts money from growth assets into government securities as the subscriber ages. The design insulates accumulated wealth from equity volatility near retirement.
Table 2: NPS Asset Classes (E, C, G, A) — Instruments and Portfolio Role
Lists the four NPS asset classes available under Active Choice, the instruments each holds and the role each plays in a portfolio.
| Asset Class | Instruments | Portfolio Role |
|---|---|---|
| Class E (Equity) | Equity instruments, subject to regulatory exposure caps | High growth |
| Class C (Corporate Bonds) | Debt issued by corporate and infrastructure entities | Fixed income |
| Class G (Government Securities) | Sovereign debt securities | Capital preservation and baseline yield |
| Class A (Alternative Investment Funds) | Alternative assets, including REITs and InvITs | High-yield alternatives |
Related Read: Which Banks Offer the Highest FD Rates in India? (Top Rate: 8.60% — September 2026 Update)
How Does NPS Reduce Your Income Tax Bill?
NPS tax benefits depend on the tax regime and on who makes the contribution. Personal contributions earn deductions only under the Old Tax Regime, while employer contributions under Section 80CCD(2) remain deductible under both regimes.
Section 80CCD Deductions: Old Regime vs New Regime
Under the Old Regime, a salaried employee’s Tier I contribution is deductible up to 10% of Basic Pay plus Dearness Allowance (Basic + DA) under Section 80CCD(1). Self-employed individuals can claim up to 20% of Gross Total Income.
Those claims sit inside the ₹1,50,000 aggregate ceiling of Section 80CCE, shared with Section 80C instruments. Section 80CCD(1B) then adds an exclusive ₹50,000 deduction for voluntary Tier I contributions, lifting the personal ceiling to ₹2,00,000.
The New Regime disallows both personal deductions. Employer contributions under Section 80CCD(2) stay deductible, and Budget 2024 raised the private-sector limit from 10% to 14% of Basic + DA, matching government-sector employees.
Under the Income-tax Act, 2025, effective from FY 2026–27 onwards, the employer contribution deduction is codified as Section 124.
Table 3: NPS Tax Deduction Limits by Section, Taxpayer Type and Tax Regime
Shows the deduction ceiling under Sections 80CCD(1), 80CCD(1B) and 80CCD(2) for each taxpayer cohort in the Old and New Tax Regimes.
| Statutory Provision | Who Qualifies | Old Regime Limit | New Regime Limit | Notes |
|---|---|---|---|---|
| Section 80CCD(1) | Salaried and self-employed | Salaried: up to 10% of Basic + DA. Self-employed: up to 20% of Gross Total Income | Disallowed | Sits within the ₹1,50,000 Section 80CCE cap |
| Section 80CCD(1B) | All individual subscribers | Up to ₹50,000 | Disallowed | Exclusive NPS benefit over and above Section 80C |
| Section 80CCD(2) (Section 124 in Act 2025) | Government-sector employees | Up to 14% of Basic + DA | Up to 14% of Basic + DA | Retained across both regimes |
| Section 80CCD(2) (Section 124 in Act 2025) | Private-sector employees | Up to 10% of Basic + DA | Up to 14% of Basic + DA | Private-sector limit raised under the New Regime |
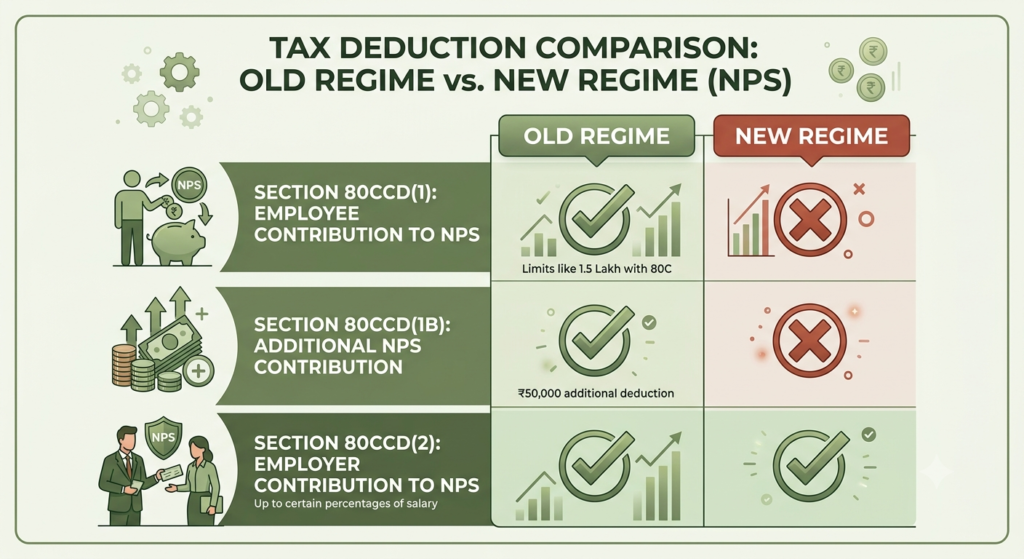
Infographic: Which NPS deductions survive in the New Tax Regime and which do not.
Related Read: Why Is HDFC ERGO Insurance So Expensive? The 84–89% Claim Ratio Behind the Price (2026)
Employer Contribution Example: 10% vs 14% on a ₹12 Lakh Salary
Consider a private-sector professional with annual Basic + DA of ₹12,00,000 in the 30% tax bracket. Adding the 4% Health and Education Cess gives an effective rate of 31.2%, before any surcharge.
Table 4: Employer NPS Contribution Tax Saving at 10% vs 14% (₹12,00,000 Basic + DA, 31.2% Effective Rate)
Calculates the deductible employer contribution and resulting tax saving under the earlier 10% limit and the enhanced 14% limit in the New Tax Regime.
| Metric | 10% Employer Contribution | 14% Employer Contribution | Difference |
|---|---|---|---|
| Employer contribution (Basic + DA × rate) | ₹1,20,000 | ₹1,68,000 | +₹48,000 |
| Tax saved (contribution × 31.2%) | ₹37,440 | ₹52,416 | +₹14,976 |
Moving from 10% to 14% adds ₹14,976 in annual tax savings. The change also directs an extra ₹48,000 into the employee’s long-term retirement fund.
Related Read: <a href=”/employer-nps-contribution-section-80ccd2/”>Employer NPS Contribution (Section 80CCD(2)): How to Claim the 14% Deduction</a>
The ₹7.5 Lakh Perquisite Ceiling
Section 17(2)(vii) of the Income Tax Act caps the tax-free combined employer contribution to EPF, NPS and approved superannuation funds at ₹7,50,000 a year. Anything above becomes a taxable perquisite, and returns on the excess are taxed annually as well.
Assume a standard employer EPF contribution of 12% of Basic Pay. A 14% NPS contribution then crosses the ceiling at roughly ₹29,00,000 of annual Basic + DA. Below that level, the full 14% flows into the pension corpus without perquisite tax.
Who Can Open an NPS Account? Age Limits and Ineligible Categories
Any Indian citizen aged 18 to 70, whether resident, Non-Resident Indian (NRI) or Overseas Citizen of India (OCI), can open an NPS account. In December 2025, PFRDA raised the maximum entry age from 65 to 70 and extended the continuation limit to 85.
Entry Age, Continuation Rights and Late-Entrant Exit Rules
Subscribers who join before turning 70 can keep contributing, or defer withdrawals, until age 85. Senior investors can therefore defer taxation on gains while compounding inside a regulated shelter.
For those joining between 60 and 70, PFRDA removed the historic 3-year mandatory lock-in. Late entrants can request an exit at any time.
Non-government subscribers entering after 60 under the All Citizens or Corporate Models can commute up to 80% of the corpus as a lump sum, with 20% reserved for an annuity. Under Section 10(4A), up to 60% of the corpus stays tax-exempt.
Any commuted portion between 60% and 80% is taxed at marginal income tax rates unless redirected into approved channels.
Table 5: NPS Eligibility by Category — Entry Age, Continuation Ceiling and Restrictions
Summarises the minimum entry age, maximum entry age, continuation ceiling and ineligibility rules for each demographic cohort.
| Category | Minimum Entry Age | Maximum Entry Age | Continuation Ceiling | Rules and Restrictions |
|---|---|---|---|---|
| Resident Indian Citizens | 18 years | 70 years | 85 years | Full access to Tier I and Tier II; single PRAN enforced |
| Non-Resident Indians (NRIs) | 18 years | 70 years | 85 years | Valid Indian passport and active NRE/NRO bank account required |
| Overseas Citizens of India (OCIs) | 18 years | 70 years | 85 years | Valid OCI documentation required; standard PFRDA investment norms apply |
| Minors (under 18) | N/A | N/A | N/A | Ineligible for standard NPS; eligible only via guardian-managed NPS Vatsalya |
| PIOs and Foreign Nationals | N/A | N/A | N/A | Ineligible unless NRI or OCI status is documented |
| Senior Citizens (over 70) | N/A | N/A | 85 years | No new accounts; pre-existing accounts may continue to 85 |
Who Cannot Open a Standard NPS Account?
PFRDA excludes six groups from opening a standard account, mainly to enforce statutory compliance and one-account-per-person discipline:
- Minors under 18: Guardians can instead open an NPS Vatsalya account, introduced in Budget 2024, which converts into a standard PRAN at 18 after KYC validation.
- Individuals above 70: Persons who have reached 71 cannot open new accounts, though accounts opened earlier can continue.
- Foreign nationals and PIOs without OCI status: Only NRIs and OCIs with valid documents qualify.
- Non-individual entities: HUFs, trusts, corporates, partnership firms and associations of persons cannot hold a PRAN. Corporates may only make employer contributions for individual employees.
- Existing PRAN holders: A “One Citizen, One PRAN” policy applies, and secondary accounts flagged by Central Recordkeeping Agencies (CRAs) are frozen.
- Undischarged insolvents and legally incapacitated persons: Individuals unable to enter binding contracts are ineligible.
Which Bank Is Best for NPS?
No bank manages your NPS money, so no bank changes your investment returns. Returns depend on the Pension Fund Manager (PFM) you select, while the bank only determines the quality of service.
Three Roles: POP, Trustee Bank and Pension Fund Manager
Financial institutions play three distinct, regulated roles in the NPS ecosystem. Confusing them is the main reason “best bank for NPS” searches mislead investors.
Table 6: Who Does What in NPS — Points of Presence, Trustee Bank and Pension Fund Managers
Explains the function of each NPS intermediary and names the institutions that currently fill the role.
| Role | Function | Examples |
|---|---|---|
| Point of Presence (POP) | Retail interface for onboarding, KYC, service requests and contribution routing | SBI, HDFC Bank, ICICI Bank, Axis Bank, Canara Bank |
| Trustee Bank | Clearinghouse that receives funds across channels, matches data with CRAs and distributes capital to PFMs | Axis Bank |
| Pension Fund Manager (PFM) | Manages asset allocation across Class E, C, G and A | SBI Pension Funds, HDFC Pension Management, ICICI Prudential Pension Funds |
Show Image
Infographic: How a rupee moves from the subscriber through the POP and Trustee Bank to the Pension Fund Manager.
Four Criteria for Choosing a POP Bank
Because growth is driven by the PFM and markets, selecting a POP comes down to operational efficiency. Four criteria matter most:
- Digital integration and eNPS capability: Direct net-banking and app integration allow voluntary contributions without gateway fees or manual clearing delays.
- D-Remit support: Strong POPs simplify static Virtual Account ID setup and automated Standing Instructions (SIPs).
- Turnaround time: Automated KYC and processing pipelines speed up PRAN verification and activation.
- Physical branch coverage: A wide network helps subscribers who prefer offline service for address updates or beneficiary changes.
PFM choice is independent of the POP. Subscribers can switch PFMs once per financial year and adjust their asset allocation up to four times per financial year without tax penalties.
How Do Lump Sum NPS Investments Work?
Subscribers can invest a lump sum in Tier I or Tier II at any time. NPS imposes no fixed monthly obligation, and the only floors are ₹250 to open an account and ₹10 per later transaction.
D-Remit: Lump Sums Through a Virtual Account ID
The Direct Remittance (D-Remit) framework removes payment-gateway clearing delays. A subscriber generates a static Virtual Account Number linked to their PRAN with the Trustee Bank.
The sixth digit identifies the account: ‘1’ for Tier I and ‘2’ for Tier II. Once the Virtual ID is added as a beneficiary in a banking portal, contributions move via NEFT, RTGS or IMPS, or through a Standing Instruction. The minimum per D-Remit transaction is ₹500.
The 1:30 PM Same-Day NAV Cut-off
PFRDA Circular No. PFRDA/2026/42/REG-PF/08, issued August 4, 2026, moved the daily cut-off for same-day NAV allocation from 11:00 AM to 1:30 PM on business settlement days.
The rule covers eNPS, D-Remit, UPI, Bharat Bill Payment System (BBPS), POPs, STAR NPS and Tatkal NPS. To secure that day’s closing NAV, the contribution must be cleared, received and matched by the Trustee Bank before 1:30 PM.
Table 7: NPS Same-Day NAV Rules by Contribution Timing
Shows which NAV applies to a contribution depending on when the Trustee Bank receives it.
| Contribution Scenario | NAV Applied |
|---|---|
| Cleared and matched by the Trustee Bank before 1:30 PM on a business settlement day | Closing NAV of the payment date |
| Received by the Trustee Bank after 1:30 PM | Closing NAV of the next business settlement day |
| Transferred on a Saturday, Sunday or public bank holiday | Closing NAV of the next business settlement day |
How Does NPS Exit and Withdrawal Work?
At age 60 or superannuation, subscribers can withdraw up to 60% of the Tier I corpus as a tax-free lump sum under Section 10(4A). The remaining 40% must buy an annuity from an IRDAI-empanelled Annuity Service Provider to generate a regular monthly pension.
Exit terms shift with entry age, sector and corpus size. Two small-corpus waivers also apply.
Table 8: NPS Exit Scenarios — Lump Sum Limits, Annuity Requirements and Conditions
Compares the maximum lump sum and minimum annuity across normal exit, small-corpus exit, late-entrant exit, premature exit and Tier II withdrawal.
| Exit Scenario | Maximum Lump Sum | Minimum Annuity | Conditions |
|---|---|---|---|
| Normal exit at 60 or superannuation | 60% (tax-free under Section 10(4A)) | 40% | Annuity from an IRDAI-empanelled provider |
| Tier I corpus of ₹8,00,000 or less at 60 | 100% (tax-free) | Waived | Mandatory annuity rule waived entirely |
| Late entrant joining after 60 (non-government, All Citizens or Corporate Model) | 80% | 20% | No lock-in; up to 60% tax-exempt, 60–80% taxed at marginal rates unless redirected to approved channels |
| Premature exit before 60 | 20% | 80% | Minimum 5-year lock-in |
| Premature exit with corpus of ₹5,00,000 or less | 100% | Waived | Full corpus withdrawable as lump sum |
| Tier II account | 100% | None | No mandatory annuity purchase |
Policy, Payroll and Personal Finance: Three Views on NPS Reform
Regulator’s View: Wider Coverage, Longer Working Lives
Raising entry to 70, continuation to 85 and introducing NPS Vatsalya for minors all point in one direction. PFRDA is stretching NPS across the full arc of life, from childhood accounts to late-career entrants.
Parity between private and public employer deduction limits removes a structural gap. The 1:30 PM cut-off further aligns NAV timing with real banking flows.
Employer and Intermediary View: Payroll Design and Processing
For employers, the 14% limit widens salary-structuring room in the New Regime. The Section 17(2)(vii) ceiling still constrains high-salary packages, especially when a 12% EPF contribution sits alongside NPS.
POPs and the Trustee Bank now work with a longer same-day window. Static Virtual IDs and Standing Instructions make recurring corporate remittances easier to automate.
Subscriber View: Flexibility With Trade-Offs
A corporate employee gains the most from the enhanced Section 80CCD(2) deduction. A senior citizen gains a regulated place to keep compounding capital past 65, and a retail investor gains flexible lump-sum access through D-Remit.
Trade-offs remain. Tier I stays locked until 60 unless a permitted exit applies, at least 40% of a normal-exit corpus must become an annuity, and returns move with markets.
What the 2026 NPS Changes Mean for Your Retirement Plan
NPS has evolved from a civil-service pension model into a flexible investment platform for retirement planning. Low-cost, market-linked growth combines with structured tax incentives across both tax regimes.
Employees should check whether their employer offers a Section 80CCD(2) contribution, since it is the one NPS deduction that survives in the New Regime. Late starters now have until 70 to enter and until 85 to stay invested.
Investors making lump-sum contributions should aim to have money cleared before 1:30 PM on a business day. Before any decision, confirm the latest rules with PFRDA circulars and your chosen POP.
NPS FAQs
What is the minimum amount to open an NPS account?
Can I claim an NPS tax deduction in the New Tax Regime?
What is the maximum age to join NPS?
Can NRIs and OCIs open an NPS account?
What is the NPS same-day NAV cut-off time?
How much can I withdraw from NPS at age 60?
Sources and References
- PFRDA Increased the NPS Entry Age from 65 to 70 Years — AffairsCloud
- NPS Same-Day Investment: Cut-off Time Now 1:30 PM — FormatPotter
- NPS Scheme 2026: Extended Entry Age, Higher Liquidity and Tax — Protean
- NPS — Personal Banking — State Bank of India
- Budget 2024: Deduction Limit Increased from 10% to 14% — Mint
- Union Budget: NPS Taxation Changed After Budget 2024 — Business Today
- Employer NPS Deduction: How to Claim Tax Benefit in the New Regime — Value Research
- Key Amendments in PFRDA (Exits and Withdrawals under the NPS) — PIB
- Invest in NPS for NRIs and OCI Online — DSP Pension Fund
- Same Day NAV and D-Remit — NPS CRA (Protean)
About the Author
Prathamesh C. is a Financial Analyst who writes about personal finance, taxation and retirement planning in India.