
Is There a 0% Interest Home Loan in India? What’s Actually Available (Up to ₹1.80 Lakh in Real Subsidy)
By Prathamesh C., Financial Analyst · 8 min read · Published September 27, 2026
Disclaimer: This article is for educational purposes only and should not be construed as formal financial advice. Subsidy amounts, tax provisions, and regulatory rules cited are current as of publication and subject to change — verify current terms with your lender, a chartered accountant, or the official PMAY-U portal before acting.
Key Takeaways
- No Indian bank can legally offer a true 0% interest home loan — RBI rules prohibit zero-interest commercial credit outright.
- The closest real equivalent is PMAY-U 2.0’s Interest Subsidy Scheme: a 4% subvention on the first ₹8 lakh of principal, worth up to ₹1.80 lakh, paid directly into your loan account.
- Interest-free alternatives exist outside banks too — Sharia-compliant cooperatives, private AIFs, and tax-exempt intra-family loans — each with its own eligibility maze.
Type “0% interest home loan India” into Google and you’ll get a wall of confident-sounding ads. Here’s the blunt answer: no scheduled commercial bank in India can legally offer a genuine zero-interest home loan. Banks price in the cost of capital, credit risk, and inflation on every rupee they lend — a rule enforced directly by the Reserve Bank of India. But that doesn’t mean interest-free homeownership is a myth. It just doesn’t come from a bank counter — it comes from three very different places: a government subsidy scheme, non-bank interest-free financing structures, and private family lending.
The Short Answer: No True 0% Loan, But a Real ₹1.80 Lakh Subsidy Exists
The government’s functional stand-in for a 0% loan is Pradhan Mantri Awas Yojana – Urban 2.0 (PMAY-U 2.0), running from September 1, 2024, to August 31, 2029. Under its Interest Subsidy Scheme (ISS) vertical, the government doesn’t waive your EMI — it pays a chunk of your interest cost directly into your loan account, shrinking your outstanding principal over time.
Who Qualifies for the PMAY-U 2.0 Interest Subsidy
Eligibility is income-tiered. Economically Weaker Sections (EWS) earn up to ₹3 lakh a year, Low-Income Groups (LIG) earn ₹3–6 lakh, and Middle-Income Groups (MIG) earn ₹6–9 lakh. All three tiers get the same benefit structure — what changes is who qualifies to apply.
| Parameter | EWS | LIG | MIG |
|---|---|---|---|
| Annual household income | Up to ₹3 lakh | ₹3–6 lakh | ₹6–9 lakh |
| Subsidised interest rate | 4% p.a. on the first ₹8 lakh of principal | 4% p.a. on the first ₹8 lakh of principal | 4% p.a. on the first ₹8 lakh of principal |
| Max eligible home loan | ₹25 lakh | ₹25 lakh | ₹25 lakh |
| Max property value | ₹35 lakh | ₹35 lakh | ₹35 lakh |
| Max carpet area | 120 sq. metres | 120 sq. metres | 120 sq. metres |
| Max total subsidy | ₹1.80 lakh | ₹1.80 lakh | ₹1.80 lakh |
How the ₹1.80 Lakh Benefit Is Calculated and Paid
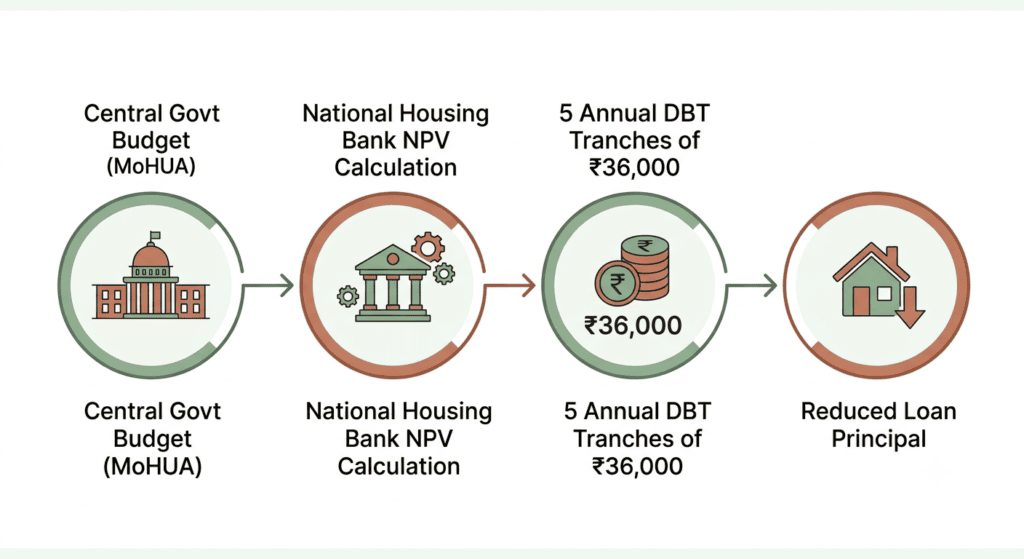
The National Housing Bank doesn’t just knock 4% off your interest bill monthly. It calculates the Net Present Value of that subvention at an 8.5% discount rate over a 12-year horizon, caps it at ₹1.80 lakh, and releases it as Direct Benefit Transfer — five annual instalments of ₹36,000 each, straight into your loan account. Each instalment immediately cuts your outstanding principal, which lowers either your EMI or your remaining tenure.
Conditions That Can Forfeit Your Subsidy
The fine print matters. Your loan must stay standard and performing, with more than 50% of the principal still outstanding at each tranche date. Property title must generally sit with an adult female household member (solely or jointly) — sole male ownership is allowed only for widowers, unmarried applicants, legally separated individuals, transgender beneficiaries, or households with no adult female. The property must fall within a Census 2011 Statutory Town, and geo-tagging on the government’s Unified Web Portal must be completed before the fourth tranche is released. Transfer your loan to another lender mid-way, and you forfeit every remaining instalment.
📎 Related read: Why Is HDFC ERGO Insurance So Expensive? The 84–89% Claim Ratio Behind the Price (2026)
Why “0% Interest” and “No-Cost EMI” Ads Are Not What They Seem
Retail and developer financing ads often promise “0% interest” or “No-Cost EMI.” Under RBI’s 2013 circular and its Master Direction on Credit and Debit Card Issuance, this is technically not allowed to mean what it sounds like. What actually happens is a merchant subvention: the seller forgoes the cash discount they’d otherwise offer and pays that amount to the financing bank instead. The bank still earns its full risk-adjusted return — you simply pay the undiscounted list price instead of seeing interest as a separate line item. One genuine consumer win did land recently: from June 15, 2025, penal interest on late EMI payments is banned across all loan categories, so lenders can no longer compound punitive charges on overdue balances.
| Feature | PMAY-U 2.0 Subvention | “No-Cost EMI” | Conventional Mortgage |
|---|---|---|---|
| True interest cost | Effectively reduced by 4% on first ₹8L | Standard 12–16% p.a., hidden in price | Market rate, ~8.5–10.5% p.a. |
| Who funds it | Central government (MoHUA) budget | Merchant margin / OEM subvention | Bank deposits & wholesale debt |
| Effect on you | Principal reduced by direct credit | You forfeit the cash discount | You bear the full interest cost |
| Regulatory status | Mandated public housing policy | Zero-interest claims banned by RBI | Standard RBI lending norms |
Is There a Sharia-Compliant, Interest-Free Home Loan in India?
In Islamic jurisprudence, interest (Riba) is impermissible, so financing has to run through asset-backed trade, leasing, or profit-sharing instead of a straight loan. India’s commercial banking law makes this structurally hard inside a scheduled bank.
Why the Banking Regulation Act Blocks Islamic Home Finance
Four sections of the Banking Regulation Act, 1949 do the blocking. Section 5(b) defines banking strictly as deposit-taking for lending, ruling out risk-sharing deposit models (Mudarabah, Musharakah). Section 8 bars banks from trading goods, which rules out cost-plus resale financing (Murabaha). Section 9 caps how long a bank can hold immovable property, blocking lease-to-own structures (Ijara wa Iqtina). And Section 21 ties lenders to RBI-set policy rates rather than flexible rental yields. Two RBI-linked panels — the 2008 Committee on Financial Sector Reforms and the 2015 Committee on Medium-Term Path for Financial Inclusion — separately recommended allowing “interest-free windows” at commercial banks after studying models like Malaysia’s. The government has not issued the statutory notifications needed to act on either recommendation.
Where Interest-Free Financing Actually Operates Today
Because banks can’t offer it, non-bank entities fill the gap. Multi-State Cooperative Credit Societies — such as the Al-Khair Cooperative Credit Society in Patna and networks under Sahulat Microfinance — pool member share capital and non-interest deposits, then extend interest-free micro-loans and joint housing credit, covering costs through flat processing fees instead of interest. Separately, SEBI-registered Alternative Investment Funds and private equity vehicles, such as Secura Housing in Kerala or funds structured by Mount Judi Ventures and Rehbar Financial Services, buy real estate directly and share rental yield or capital appreciation with homebuyers under equity-partnering models.
| Model | Governing law | Mechanism | Examples |
|---|---|---|---|
| Cost-plus resale (Murabaha) | BR Act, Sec 8 — barred in banks | Financier buys, resells at fixed markup in instalments | Private trade arrangements only |
| Lease-to-own (Ijara wa Iqtina) | BR Act, Sec 9 — barred in banks | Financier holds title, transfers on final payment | Specialised private agreements |
| Cooperative credit | Multi-State Coop. Societies Act, 2002 | Member share capital funds interest-free credit | Al-Khair, Sahulat network |
| Private equity / AIF | Companies Act / SEBI AIF Regulations | Investors share rental yield & appreciation | Secura Housing, Mount Judi, Rehbar |
📎 Related read: Which Banks Offer the Highest FD Rates in India? (Top Rate: 8.60% — September 2026 Update)
What If You Borrow From Family Instead?
A genuinely interest-free loan from parents to a major child is legal — but it lives inside a fairly strict tax and cash-handling framework.
How Family Loans Are Taxed
The Income Tax Act treats the loan principal as a capital receipt, not income, for the borrower — because it comes with an unconditional obligation to repay. The lender isn’t taxed on any “notional interest” either; that concept only applies to employer-employee perquisites, not private family loans. If the recipient is a major (18+), the clubbing provisions under Section 64(1)(iv) don’t apply, so any rental income or capital gains the child later earns from a property bought with that loan are taxed solely in the child’s hands.
The ₹20,000 Cash Rule You Cannot Ignore
Where families get burned is cash. Section 269SS bans accepting ₹20,000 or more in cash as a loan or deposit connected to property — it must move via cheque, DD, ECS, NEFT, RTGS, IMPS, or UPI. Section 269T applies the identical rule to repayment. Breach either one and the penalty is severe: 100% of the cash amount under Section 271D (receiving) or Section 271E (repaying), levied by the Joint Commissioner of Income Tax. Tax auditors are required to flag such transactions under Form 3CD.
There is a narrow escape hatch. Section 273B allows a “reasonable cause” defence, and tribunals have used it: in Smt. Meera Devi Kumawat v. JCIT (ITAT Jaipur, 2021), a penalty was struck down because the cash was a genuine pooling of family funds for a home purchase, not a commercial loan. But the burden of proof sits entirely with the taxpayer — the safer move is always a traceable bank transfer.
Frequently Asked Questions
Does any Indian bank offer a genuine 0% interest home loan? No. RBI regulations prohibit commercial banks from offering zero-interest credit products of any kind, including home loans.
What is the maximum PMAY-U 2.0 subsidy I can get? Up to ₹1.80 lakh, calculated as the net present value of a 4% interest subvention on the first ₹8 lakh of your loan principal, paid in five annual instalments of ₹36,000.
Is an interest-free loan from my parents taxable? The loan principal itself is not taxable as income for either party. However, cash transactions of ₹20,000 or more attract a 100% penalty under Sections 271D/271E — use a bank transfer instead.
Can I get a Sharia-compliant home loan from a bank in India? Not from a scheduled commercial bank — the Banking Regulation Act, 1949 blocks the underlying structures. Interest-free financing is available instead through cooperative credit societies and SEBI-registered private investment vehicles.
Put together, “interest-free” in India isn’t one product — it’s a set of narrow doors: a capped government subsidy for eligible urban buyers, a small cluster of cooperative and private-equity alternatives for those seeking Sharia compliance, and a tax-clean but cash-restricted path through family lending. Whichever door fits, the paperwork and the rules matter more than the marketing.
Prathamesh C. — Financial Analyst Covers Indian mortgage policy, alternative financing, and personal finance.
One Comment